Investment banking is one of the most profitable and least understood industries in the world. Goldman Sachs, JPMorgan, Morgan Stanley — these institutions sit at the center of global capital markets, facilitating the transactions that move trillions of dollars between corporations, governments, and investors. They charge enormous fees for doing so. And for decades, there was simply no alternative.
DeFi is changing that. Not all at once, not without friction, and not without limitations — but systematically, protocol by protocol, the functions that investment banks have charged premium fees to perform are being rebuilt on open, permissionless blockchain infrastructure.
This isn't a prediction about the future. It's a description of what's already happening.
Before understanding how DeFi disrupts investment banking, it helps to understand what investment banks actually do — beyond the general impression of expensive suits and large bonuses.
Investment banks perform several core functions in the financial system:
Capital raising — helping companies access capital by underwriting stock offerings (IPOs) and bond issuances. The bank acts as intermediary between the company that needs capital and the investors who have it, taking a significant fee for facilitating the connection.
Market making — providing liquidity in financial markets by continuously quoting buy and sell prices for securities, profiting from the spread between them. This function keeps markets liquid and prices stable.
Asset management — managing investment portfolios for institutional and high-net-worth clients, charging management fees and performance fees for doing so.
Custody — holding assets on behalf of clients, ensuring they’re properly accounted for and secured.
Trading — executing trades on behalf of clients and for the bank’s own account, using sophisticated systems and privileged market access.
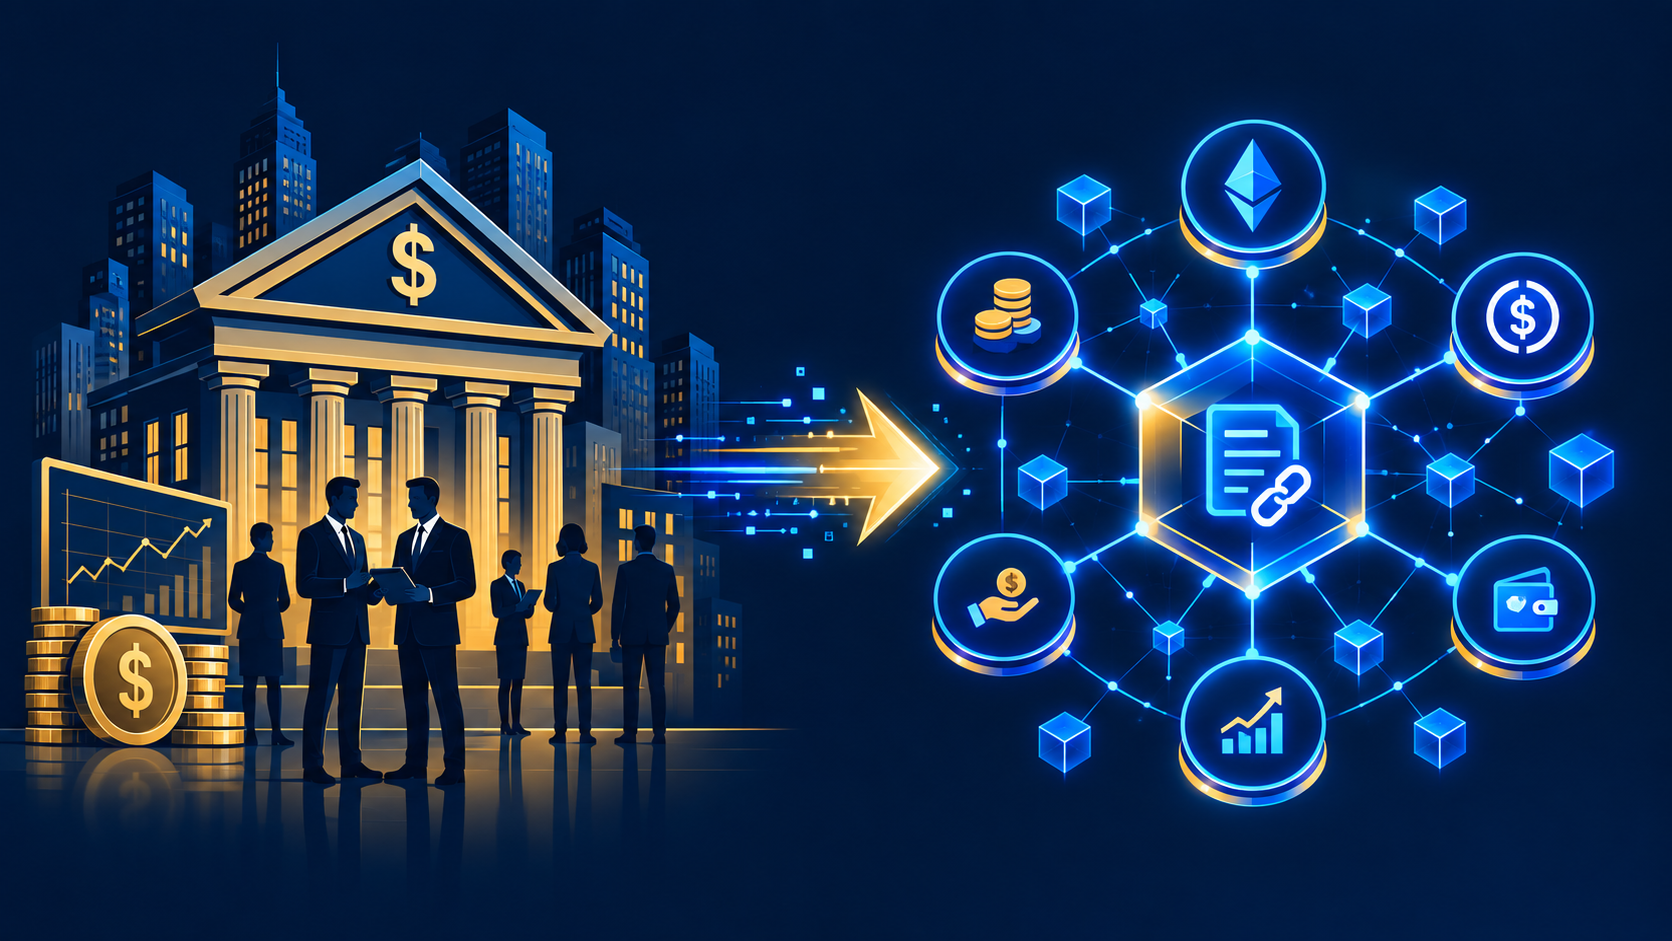
Each of these functions involves the bank sitting in the middle of a transaction, adding value by providing access, liquidity, or trust — and extracting fees accordingly. DeFi is rebuilding each of these functions, removing the bank from the middle.
Traditional capital raising is a lengthy, expensive, and exclusive process. A company seeking to raise capital through a public stock offering pays underwriting fees typically ranging from 3–7% of the total raise. The process takes months and requires relationships with investment banks, lawyers, accountants, and regulators. Access to participate as an investor is gated — institutional allocations go to favored clients, retail investors get whatever’s left after the insiders have taken their positions.
DeFi has introduced an entirely different model. Token launches — whether through Initial DEX Offerings (IDOs), liquidity bootstrapping pools, or direct listings on decentralized exchanges — allow projects to raise capital directly from their community, globally, instantly, with no investment bank taking a percentage of the raise.
The mechanics vary by approach, but the principle is consistent: smart contracts replace the underwriter. Liquidity pools replace the road show. Community participation replaces institutional allocation. And the fees that would have gone to the bank go instead to the protocol’s treasury or directly to early participants.
This model has real limitations — token launches have been associated with significant fraud and speculation, regulatory frameworks are still developing, and the quality of due diligence available to participants is lower than in traditional markets. But the direction is clear: capital formation is becoming permissionless, and the investment bank’s role as gatekeeper is being challenged at the foundation.
Market making — providing continuous buy and sell liquidity to keep markets functioning — has historically required significant capital, sophisticated technology, and privileged exchange relationships. Large investment banks and specialized market-making firms dominated this function, profiting from spreads and their informational advantages.
Automated Market Makers — the technology underlying Uniswap, Curve, and every other major DEX — democratized market making entirely.
As we covered in our guides on Liquidity Pools and DEXs, anyone with capital can now provide liquidity to trading pairs and earn the spread as trading fees. The mathematical formula that governs AMM pricing — x × y = k — performs the same market-making function that investment bank trading desks do, automatically, transparently, and without the need for any privileged participant.
The scale is no longer trivial. Uniswap alone has processed over $2 trillion in lifetime trading volume. Curve Finance has become essential infrastructure for stablecoin liquidity. The market-making function that banks once monopolized is now performed by a distributed network of liquidity providers earning fees in proportion to their contribution — with no bank taking a cut.
Traditional asset management charges investors ongoing fees — typically 1–2% annually for actively managed funds — for the service of deploying their capital into return-generating strategies. The manager has discretion over how capital is allocated, and investors trust the manager to act in their interests.
DeFi has introduced a new model: automated yield vaults that execute investment strategies through smart contracts, charge dramatically lower fees, and operate with complete transparency about exactly how every dollar is being deployed.
Yearn Finance — one of the earliest and most influential examples — automatically moves deposited capital to wherever the best yield is available across the DeFi ecosystem, rebalancing continuously as opportunities shift. The strategy is encoded in smart contracts that anyone can read and verify. The fees are a fraction of what traditional asset managers charge. And the performance is visible in real time, not in quarterly reports.
More sophisticated vault strategies have followed — protocols that automate liquidity provision, harvest and compound yield farming rewards, manage collateral ratios on borrowing positions, and execute complex multi-protocol strategies that would require significant expertise to manage manually.
The gap between what these automated vaults can do and what a traditional fund manager provides is narrowing — and the fee differential between them is enormous and growing.
Institutional custody — the secure holding of financial assets on behalf of clients — is a significant business for investment banks and their affiliated prime brokerage operations. Clients pay for the assurance that their assets are held securely, properly accounted for, and accessible when needed.
In DeFi, custody is self-managed by default. As we’ve covered throughout this blog, self-custodied wallets — secured by private keys that only the owner controls — remove the custodian from the equation entirely. There’s no prime broker holding your assets, no counterparty risk from the custodian’s own financial health, and no fees paid for the privilege of someone else holding your money.
Hardware wallets like Ledger and Trezor provide institutional-grade security for individual users at a fraction of the cost of prime brokerage custody. Multi-signature wallet structures — requiring multiple private keys to authorize any transaction — replicate the security controls of institutional custody without any centralized intermediary.
For institutions specifically, specialized DeFi custody solutions are emerging that combine the security of on-chain self-custody with the compliance frameworks and insurance structures that institutional participants require. The custody function isn’t disappearing — it’s being rebuilt on infrastructure that doesn’t require trusting a prime broker with your assets.
Investment banks have historically enjoyed significant advantages in trading — access to order flow, relationships with exchanges, sophisticated technology, and the ability to trade ahead of markets in ways that retail participants cannot replicate.
DeFi markets are fundamentally different. Every participant interacts with the same smart contracts, at the same prices, with the same access. There’s no preferential order routing, no dark pools where institutional orders get filled ahead of yours, no proprietary information about pending order flow.
This doesn’t mean DeFi trading is perfectly fair — MEV (Maximal Extractable Value) creates its own asymmetries, as sophisticated bots front-run transactions in the public mempool. But the structure of the advantage is different: it’s available to anyone who builds the right infrastructure, not reserved for institutions by their exchange relationships.
The broader point is that DeFi has created trading markets that operate on publicly verifiable rules, execute at publicly visible prices, and provide the same access to a first-time participant with $100 as to an institution with $100 million. That’s a structural change in how financial markets work — and it represents a meaningful challenge to the privileged position investment banks have occupied.
The most concrete measure of DeFi’s disruption of investment banking is the fee comparison.
An IPO underwriting fee: 3–7% of the raise.
A DEX token listing fee: essentially zero.
A traditional asset management fee: 1–2% annually plus performance fees.
A DeFi yield vault fee: 0.1–0.5% annually.
A prime brokerage custody fee: basis points on assets under custody plus transaction fees.
A self-custodied hardware wallet: a one-time purchase of $79–$279.
A wire transfer fee for international capital movement: $25–$50 plus FX spread.
A stablecoin transfer on Layer 2: $0.01–$0.05.
These aren’t marginal differences. They’re order-of-magnitude differences in the cost of accessing core financial services — and they accumulate enormously over time for anyone moving significant capital.
Intellectual honesty requires acknowledging where traditional investment banking still has genuine advantages over DeFi.
Regulatory compliance. Investment banks operate within established legal frameworks that institutional clients — pension funds, insurance companies, sovereign wealth funds — are legally required to use. Until DeFi develops equivalent compliance infrastructure, much institutional capital will remain in traditional markets.
Complex advisory services. Mergers and acquisitions, structured finance, and complex capital restructuring require judgment, relationships, and expertise that smart contracts can’t replicate. The advisory function of investment banking — not just the execution — has genuine value that automation hasn’t touched.
Client relationships and trust. Established investment banks have decades of relationship capital with the world’s largest institutions. That trust doesn’t transfer overnight, and building equivalent trust in DeFi protocols takes time — measured in market cycles, not quarters.
Fiat on and off ramps. DeFi operates natively in crypto. Moving large amounts of capital between the traditional financial system and DeFi still requires intermediaries — banks, regulated exchanges, and custodians — that investment banks are well-positioned to provide.
The most realistic picture of where this leads isn’t DeFi replacing investment banking — it’s DeFi forcing investment banking to change.
The largest banks are already moving in this direction. JPMorgan’s blockchain infrastructure. BlackRock’s tokenized funds. Goldman Sachs’ digital asset trading desk. These aren’t defensive gestures — they’re institutions recognizing that the infrastructure underlying their business is changing and positioning accordingly.
The likely outcome is a hybrid financial system where the most commoditized banking functions — routine capital raising, market making, asset management — are increasingly performed by DeFi protocols at dramatically lower cost, while the more complex advisory and relationship functions remain with human institutions.
For everyone operating in financial markets — whether as an investor, a business owner, or simply someone trying to build wealth — understanding this shift matters. The tools being built in DeFi today are the infrastructure of the financial system being built for tomorrow.
Investment banking built its business on being the indispensable middleman in financial markets — the institution with the access, the capital, and the relationships to make large financial transactions happen. DeFi is systematically removing the need for that middleman in function after function.
Capital raising without underwriters. Market making without trading desks. Asset management without fund managers. Custody without prime brokers. Each of these is happening today, at scale, on public blockchain infrastructure that anyone can use.
The disruption isn’t complete, and it won’t be linear. But the direction is clear — and the gap between what DeFi can do and what investment banks charge to do is wide enough that it will keep attracting the capital and talent needed to close it.
Disclaimer: Educational content only — not investment, financial, tax, or legal advice. Cryptocurrency and DeFi involve substantial risk, including the potential for total loss of capital. See our full Terms & Conditions and Privacy Policy.